There is a version of this situation most experienced agents have encountered at least once. A client is navigating something complicated: a divorce, an estate, a dispute with a co-owner and they ask their agent to pull comps so they have a sense of what the property is worth. The agent knows the market. They want to help. They pull the CMA and share a number. What happens next is rarely the agent’s fault. But it is often the agent’s problem.
The issue is not that agents lack market expertise. Most agents who have worked a submarket for years have genuine, hard-earned knowledge of how properties are valued there. The issue is that certain contexts require a specific kind of document. One with a defined methodology, a licensed preparer, and a liability framework, and a CMA, however well-prepared, cannot stand in for it. Understanding where that line is, and how to communicate it to clients before a situation becomes complicated, is one of the more valuable things an agent can know.
The Critical Difference Between Pricing Advice and an Appraisal
A comparative market analysis is an agent’s professional tool for estimating a likely sale price range. It draws on recent comparable sales, active listings, and market knowledge to help a seller price competitively or help a buyer make an informed offer. Done well, it reflects genuine expertise and serves its intended purpose effectively.
It is not an appraisal. That distinction is not just technical, it carries legal weight.
An appraisal is developed by a licensed or certified appraiser, following a defined scope of work, with methodology that must be documented, supported, and defensible under professional standards. The appraiser is an independent third party with no financial interest in the transaction outcome. The report is designed to withstand scrutiny from a lender, a court, the IRS, or opposing counsel.
A CMA carries none of those structural characteristics. It is prepared by someone with a direct financial interest in the transaction, under no standardized methodology, with no requirement for documented analytical support. That is not a criticism of agents it reflects what a CMA is designed to do and, equally importantly, what it was never designed to withstand.
How an Ordinary CMA Can Become a Legal Liability
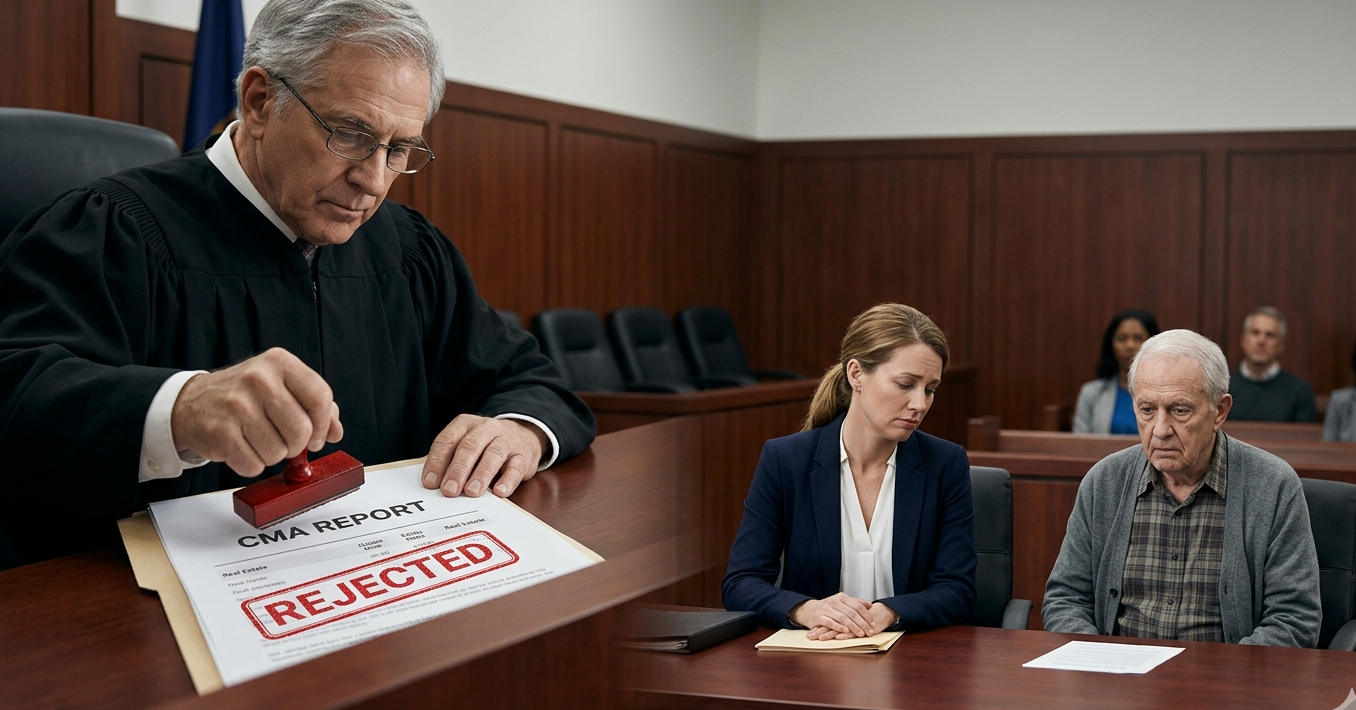
The moment the line moves is rarely obvious. It usually happens gradually, in the middle of a client relationship, when a situation that started as a standard transaction develops legal dimensions the agent didn’t anticipate. A client going through a divorce asks for comps before engaging an attorney. The agent provides them. The number gets shared in a mediation session or referenced in a settlement discussion as evidence of value a purpose it was never prepared to serve.
An estate executor, trying to manage costs, asks their agent for a CMA instead of ordering an appraisal. The number is used to distribute assets among beneficiaries. When one beneficiary later challenges the distribution, how value was established becomes the central question and the answer is a document with no legal standing as a valuation.
An agent provides a CMA in connection with a pre-foreclosure or short sale, and it later becomes relevant in a dispute over whether the lender received adequate consideration. In each case, the agent was trying to be helpful. The context changed what the document meant and the exposure followed.
What Agents Risk When a CMA Is Used Beyond Its Purpose
When a CMA is used in place of an appraisal in a legal context, the value conclusion lacks the independence and documented methodology required for it to carry evidentiary weight. Any opposing party or their counsel can point out that the person who prepared it had a financial interest in the outcome, applied no standardized methodology, and is not a licensed appraiser. That argument does not require an expert to make, and it is not difficult to make effectively.
There is also the question of the agent’s own position. Providing a valuation opinion in a context that requires a licensed appraiser may implicate state restrictions on who can provide appraisals and for what purposes. And if a CMA-based value is later shown to have materially influenced a settlement, a distribution of assets, or a financial decision, the agent who provided it may face difficult questions about their role, regardless of their intent.
None of this reflects on the agent’s knowledge or professionalism. It reflects on the mismatch between the tool and the context. That mismatch is worth understanding before it becomes relevant, not after.
Client Conversations That Protect Everyone Involved
The practical challenge is not knowing when to recommend an appraisal it is knowing how to recommend one without making the client feel like they are being handed off or asked to spend money unnecessarily. When a client’s situation involves litigation or legal proceedings, the framing can be straightforward: “For anything that’s going to be used in a legal context, you’ll want an independent appraisal rather than a CMA. An appraiser is a licensed third party with no stake in the outcome, and that independence is what gives the number credibility in front of a mediator or judge. I can refer you to someone I trust for this kind of work.”
When the situation involves estate or tax purposes, the language can focus on protection: “The IRS and the courts have specific requirements for how value needs to be established in estate matters. An independent appraisal is what satisfies those requirements and protects the estate, and your beneficiaries, from challenges later.” When a client is reluctant to incur the cost, the honest response is also the most useful one: “The cost of an appraisal is a fraction of what a challenged value conclusion costs to resolve. If there’s any chance this number is going to be disputed, the appraisal is the better investment.”
The goal is not to redirect the client away from you, it is to position yourself as the professional who understood what the situation actually required.
Knowing the Difference Builds Trust, Authority, and Referrals
Agents who can clearly articulate the distinction between a CMA and an appraisal and who proactively guide clients toward the right tool when the situation calls for it, build a different kind of professional reputation than agents who don’t.
Attorneys and CPAs who work with clients navigating divorce, estate, or litigation notice quickly which agents understand how valuation works in those contexts and which ones don’t. A referral relationship with a family law attorney or an estate planning practice is built on exactly this kind of demonstrated competence. The agent who says “you’ll need an appraisal for this, and here’s who I recommend” is the agent that attorney calls the next time their client needs to sell.
The CMA belongs at the listing table. The appraisal belongs in the file when the stakes are legal. Knowing which one the situation calls for, and being able to explain why, is not a limitation on what an agent can offer. It is an extension of what makes them worth trusting.
Protect Your Client and Strengthen Your Professional Network
When a client needs more than a pricing analysis, referring them to a qualified appraiser demonstrates sound judgment and protects the integrity of the valuation process. Contact LaPlante Appraisals to establish a trusted appraisal referral resource for divorce, estate, litigation, and complex residential assignments. Send us the property address, the purpose of the appraisal, the appropriate scope of work and we will respond less than 24 hours with a quote.